Exploring the Difference Between Minimalists and Frugalists

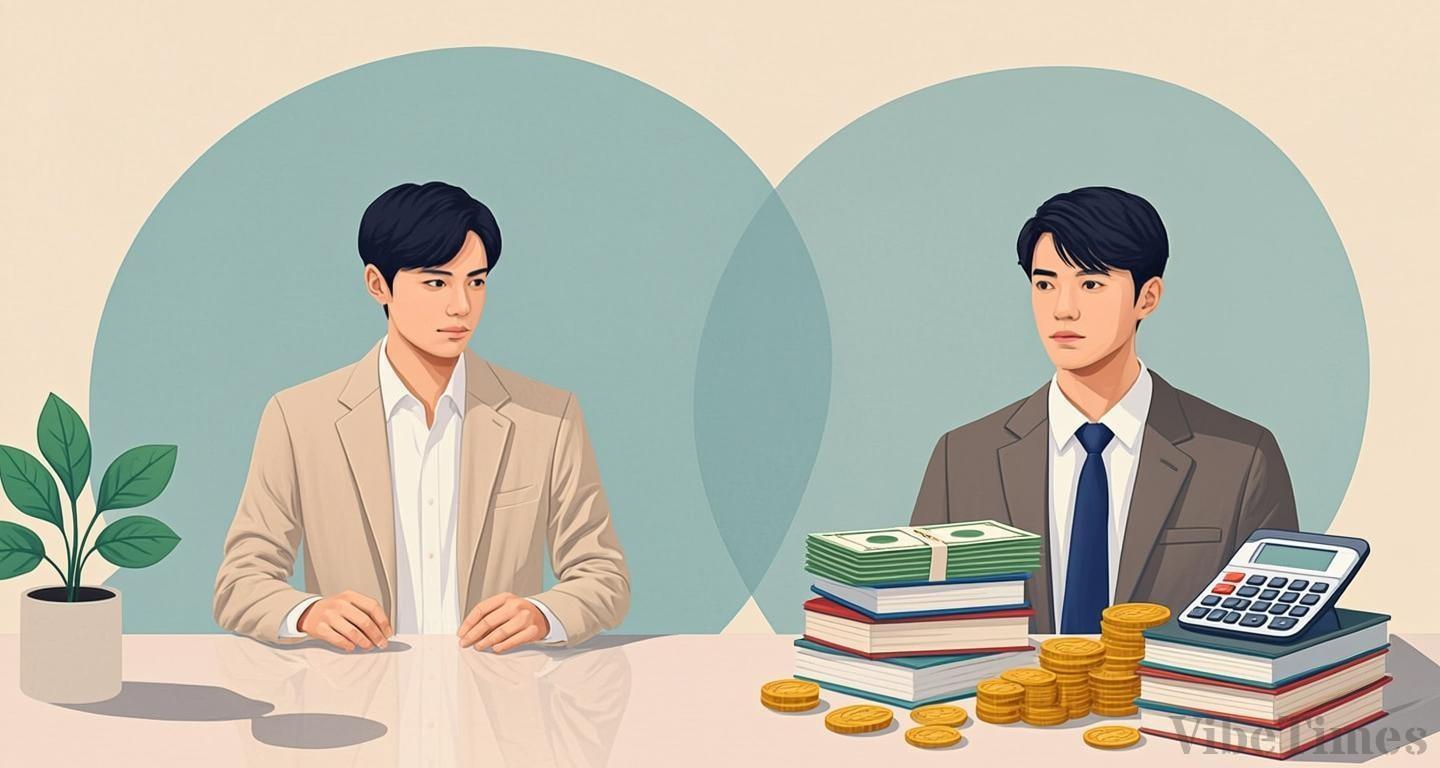
Minimalists pursue freedom of the mind, while frugalists pursue freedom of the bank account. Both approaches reduce consumption, but they start from opposite questions. The former asks, "Do I truly need this?" while the latter asks, "Can I get it for less?" Though both are forms of saving, their purposes, outcomes, and side effects differ entirely, so identifying your own priorities is the starting point for choosing between them.
Minimalism originated in the American art movement of the 1960s and spread to Korea in the 2010s amid Japan's decluttering boom. Representative practitioners include Hideyto Yamashita, author of 'I Don't Want to Own Anything,' and the American duo The Minimalists (Joshua Fields Millburn and Ryan Nicodemus). Frugality is rooted in the thrift of the Great Depression era and was revived after the 2008 financial crisis, dovetailing with the FIRE movement's pursuit of financial independence. In Korea, the two have been localized as 'decluttering culture' and 'no-spend challenges and budget-savvy savers,' respectively.
Where the Two Paths Diverge
A Fundamental Difference in Judgment
The difference becomes vivid when buying a sofa. A minimalist might choose one high-quality sofa even at a high price, while a frugalist tends to pick a cheap secondhand one. Minimalism's axis is 'quantity of possessions,' while frugality's axis is 'size of spending.' The former favors experiential spending and does not reduce spending itself, while the latter suppresses consumption altogether to build assets.
What You Gain — Comparing the Benefits
Minimalism's benefits lie in time and psychology. With fewer belongings, you can save one to three hours a week on tidying and cleaning, and with fewer clothes, morning routines shorten and decision fatigue decreases. Steve Jobs and Mark Zuckerberg wearing similar outfits are classic examples. Less luggage makes moving and travel easier, and curbed overconsumption even reduces your carbon footprint.
Frugality's strength is that it can be measured in numbers. Extreme saving allows a savings rate of 50–70% of income. By simulation, saving 50% of income leads to financial independence in about 17 years, while saving 70% takes about 8.5 years. Reduced financial stress from building an emergency fund and the formation of budgeting and bookkeeping habits are also major assets. The value of saving habits was reaffirmed during the global inflation period of 2022–2024.
Easy-to-Miss Drawbacks and Pitfalls
The Minimalist Paradox
When decluttering becomes an obsession, it actually increases stress. According to research by Jeffrey Gargas at Purdue University, extreme minimalists showed lower life satisfaction, concluding that a moderate level of minimalism is optimal. There is also the cost of discarding items only to need and repurchase them later. Critics point out the risk of it degenerating into another form of showing off, with photos of white walls and empty rooms posted on social media. There is also a practical constraint: it is hard to practice if cohabiting family members do not agree.
The Price of Frugality
Repeatedly buying cheap, low-quality products can ultimately cost more in the long run. Time spent hunting for the lowest prices and collecting coupons is also an opportunity cost. Excessive austerity can lead to underinvestment in health, relationships, and self-development, and avoiding gatherings and dining out can shrink one's social connections. 'Frugal fatigue'—burnout from sustained saving—is also a common cause of failure in practice.
The Right Choice for You and Combination Strategies
Selection Criteria and a Step-by-Step Approach
If stress relief, space, and simplicity are your priorities, minimalism is the right fit; if a concrete savings goal such as early retirement comes first, frugality suits you better. If you have many belongings and a high spending-to-income ratio, a stepwise approach—reducing possessions through minimalism first, then adding frugalist-style spending management—is effective.
For practicing minimalism, the Marie Kondo method is recommended: start with clothes, then organize books, documents, and keepsakes in that order. Discard items unused for a year, adopt a 24-hour waiting rule before purchases, and follow the 'one in, one out' rule to block inflow. For frugality, record one to three months of spending with budgeting apps like Toss or BankSalad, then save 20,000–40,000 won a month by switching to a budget phone plan, and review subscriptions and insurance. Set up an automatic transfer to save on payday first, and channel the savings into periodic investments—even the FIRE movement's 4% rule can be put to use.
A Hybrid May Be the Answer
Combining the minimalist principle of 'buy only what you need' with the frugalist strategy of 'buy what you need under optimal conditions' lets you capture the benefits of both. For example, run a full review of your belongings once or twice a year alongside no-spend days. As research by behavioral economist Daniel Kahneman and others shows, experiential spending delivers more lasting happiness than material spending. Freedom dies if unused—so whatever approach you choose, the real challenge is not choosing but sustaining.